Athlete Tax Filing in Japan: Sponsorship and Scholarships
Tax filing for athletes in Japan: how sponsorship income is classified, when scholarships and medal bonuses are tax-free, and how blue and white returns differ.
Filing taxes as an athlete in Japan is often harder than it is for a salaried employee, because income arrives from many different sources: sponsorship deals, prize money, and scholarships. Classifying any of those streams incorrectly can easily lead to underreporting or to paying more tax than you actually owe. Drawing on the National Tax Agency (NTA) explanation of employment income and tax returns, this article organizes how sponsorship income is treated, when scholarships and bonuses are taxable or tax-free, which expenses you can deduct, and how the blue and white return systems differ.
When Athletes Need to File a Tax Return
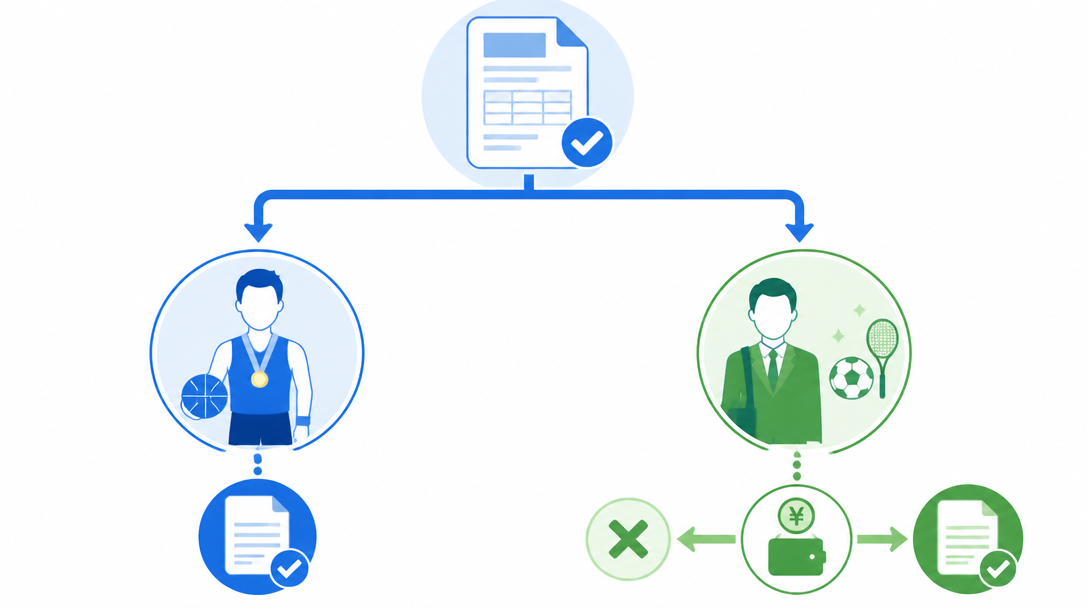
The first thing to pin down is which athletes actually have an obligation to file. Whether a return is required depends on the form your income takes and on whether competition is your main occupation or a side activity. Getting this threshold question right prevents you from either skipping a filing you were required to make or spending time on paperwork you did not need to complete.
The Basics and Who Must File
A tax return is the procedure for calculating your income and tax for the single year running from January 1 to December 31, then reporting and paying that amount to the tax office the following year. If competing is your primary source of income, as it is for professional athletes, you are in principle required to file. The NTA tax-return guide likewise treats anyone with income arising from a business or professional activity as a person subject to filing.
Company-Employed Athletes and the "200,000 Yen Rule"
Corporate-team athletes who belong to a company, draw a salary, and keep competing have their taxes settled through year-end adjustment at their workplace. As a result, if their income other than salary — sponsorship fees, appearance fees, and the like — is 200,000 yen or less for the year, they generally do not need to file. If that side income exceeds 200,000 yen, however, or if they want a refund through the medical-expense deduction or furusato nozei (hometown tax donations), a return does become necessary.
The perspective of weighing company employment against working as a sole proprietor is also covered in A Beginner's Guide to Athlete Side Businesses. It is worth understanding that how your income is structured changes the tax treatment significantly.
What Happens If You Don't File
If you have an obligation to file but fail to do so, you may be charged an additional tax for non-filing and a delinquency tax on top of the original amount due. Industry commentary on filing omissions in the sports world points to the complexity of income classification as the main reason returns get missed. The more an athlete's income spans multiple organizations and companies, the more essential early preparation becomes.
Classifying Sponsorship Income and How to File It
One of the areas where opinions most often diverge in an athlete's tax return is the income classification of sponsorship money. Depending on the form the contract takes, it is sorted into one of three categories: business income, miscellaneous income, or employment income.
Business, Miscellaneous, and Employment Income
Which category your income falls into changes the deductions and the scope of expenses available to you. The NTA has indicated, in its view on the business classification of professional athletes, that remuneration based on a contract with a team or club can qualify as business income. The main categories are as follows.
Income category | Main income it applies to | Features |
|---|---|---|
Employment income | Salary based on an employment contract with a company or team | Subject to year-end adjustment; the employment-income deduction applies |
Business income | Individually contracted sponsorship fees, prize money, and coaching fees that arise continuously and independently | Necessary expenses can be deducted; blue-return filing is available |
Miscellaneous income | One-off appearance or writing fees and other small-scale income | Expenses can be claimed, but the blue-return special deduction cannot be used |
As a basic rule of thumb, fixed remuneration based on an employment relationship is employment income, while sponsorship contracts you sign as an individual and event appearance fees are examined as business income or miscellaneous income.
How Sponsorship Money (Kyosankin) Is Treated
If you sign sponsorship contracts as an individual and receive sponsorship money on a continuous, independent basis, it is generally filed as business income. You have to recognize as income not only cash but also economic benefits such as equipment provided in kind or travel costs covered on your behalf. For the practical side of winning sponsors, A Practical Guide to Winning Sponsors explains the details.
From the sponsor's side, the sponsorship money is booked as advertising expense and is deductible, so keeping supporting documents such as contracts and invoices in order is important for both parties.
Dealing with the Invoice System
Under the invoice system (the qualified-invoice retention method) that began in October 2023, for a sponsoring company to claim an input tax credit on the consumption tax contained in the sponsorship money it pays, the athlete must be a taxable business able to issue qualified invoices. Even athletes with small revenue are increasingly being asked by sponsors to register as qualified-invoice issuers. Judge whether registration is necessary in light of your relationship with the counterparty.
Are Scholarships Taxed? The Conditions for Tax-Free Status
Scholarships, which are familiar to student athletes, are in principle not taxed. However, because the treatment changes with the nature of the grant and the source of the funding, it is important to understand the conditions accurately rather than assuming every scholarship is automatically free of tax.
Why Grant-Type Scholarships Are Tax-Free
Grant-type (non-repayable) scholarships, as set out in the NTA page "When Expenses Are Paid to Cover School Costs", fall under "money and goods granted to cover school expenses" defined in Article 9, Paragraph 1, Item 14 of the Income Tax Act, and are treated as tax-free income. You therefore do not need to report them for income tax even after you receive them. Commentary from Money Forward Cloud similarly organizes the point that grant-type scholarships are in principle not subject to income tax.
The Tax Difference Between Loan-Type and Grant-Type
Loan-type scholarships are borrowed money that must be repaid and are not income in the first place, so they are not a taxable object. Grant-type scholarships, as noted above, are tax-free income. The differences can be organized as follows.
- Loan-type (Category 1 and Category 2): tax-free because they are a liability that must be repaid; be mindful of the future repayment burden
- Grant-type (non-repayable): tax-free as school funds. The grant scholarships of the Japan Student Services Organization (JASSO) are a representative example
- Tuition reduction and exemption: reductions under the new higher-education enrollment support program are also not taxed, being an economic benefit of this kind
If you are weighing scholarships alongside enrolling at an overseas university, please also refer to Attending an Overseas University on a Sports Scholarship.
Watch Out for Taxable Cases
Even scholarships that are tax-free as a rule can become taxable in cases like the following. Note that the substance, rather than the stated label of the payment, governs the treatment.
- When you receive school funding from a corporation such as your employer and it is judged to constitute salary
- When a grant from an individual, such as a relative, exceeds 1.1 million yen a year and becomes subject to gift tax
- When the scholarship carries the character of compensation for labor and is effectively regarded as remuneration
Even in an arrangement that looks like "sports recommendation plus tuition support," the treatment changes depending on whether consideration is involved. When the judgment is difficult, confirm it with the tax office or a tax accountant.
The Line Between Taxable and Tax-Free Prize and Bonus Money
Prize money from matches and medal bonuses are also split between taxable and tax-free depending on the source of payment. In particular, Olympic and Paralympic bonuses are covered by a special tax-exemption rule of their own.
The Tax Exemption for Olympic and Paralympic Bonuses
According to materials on bonuses from the Japan Sports Agency and a column by the House of Councillors Legislative Bureau, medal bonuses paid by the Japanese Olympic Committee (JOC) and the Japanese Para Sports Association (JPSA) are tax-free under Article 9, Paragraph 1, Item 14 of the Income Tax Act and a Ministry of Finance notification. The JOC bonuses are 5 million yen for a gold medal, 2 million yen for silver, and 1 million yen for bronze.
This exemption was created in the 1994 tax reform, prompted by a case at the 1992 Barcelona Olympics in which the bonus of a swimmer who was then a junior-high-school student was taxed as temporary income. Furthermore, the fiscal-2020 tax reform made bonuses paid by the member federations (the sports governing bodies) of the JOC and JPSA tax-free as well, for the portion up to 5 million yen for gold, 2 million for silver, and 1 million for bronze.
Taxable Prize and Bonus Money
On the other hand, bonuses paid by companies, sponsors, or anyone other than the JOC, JPSA, or their member federations are taxable in principle. Prize money from domestic competitions and similar income must also be reported. Taxable prizes and bonuses are classified according to their nature as follows.
Example of income | Main income category | Tax treatment |
|---|---|---|
Medal bonuses from the JOC, JPSA, etc. | Tax-free income | Tax-free up to a set amount |
Prize money a professional earns from competition | Business income | Taxable (expenses deductible) |
One-off prize money for an amateur | Temporary or miscellaneous income | Taxable (temporary income has a special deduction) |
Bonuses or encouragement money from a company | Miscellaneous or temporary income, etc. | Taxable |
Withholding and Overseas Income
Prize money and appearance fees may already have tax withheld at the time of payment. The withheld amount is settled through your tax return, and any overpayment is refunded. In addition, prize money earned at competitions abroad may be covered by a tax treaty or the foreign tax credit, mechanisms that adjust for double taxation at home and abroad. Athletes who have overseas challenges in view can prepare on the tax side as well by also reading Language Skills and a Global Career.
Athletes' Necessary Expenses and How to File
When you file as business income or miscellaneous income, tax applies to the amount that is left after subtracting necessary expenses from your income. Correctly understanding what counts as an expense is the first step toward both proper tax payment and legitimate tax saving.
Main Items Allowed as Expenses
Spending that is directly necessary to carry out your competitive activity can be recorded as a necessary expense. Representative items are as follows.
- Travel costs: transport, lodging, and local travel for competitions and training camps
- Equipment costs: sport-specific gear, shoes, and consumables
- Training costs: gym fees, personal-coach fees, and treatment or body-care costs
- Registration costs: registration fees to governing bodies, event entry fees, and various insurance premiums
- Content costs: filming and editing equipment and outsourced production fees (when social-media activity ties into income)
Expenses that overlap with private life — clothing, communications, home rent and utilities, meals, and so on — require "household apportionment," reasonably prorating the share actually used for the business. Note that you cannot expense the full amount.
High-Value Equipment That Must Be Depreciated
Among equipment and gear, items with an acquisition cost of 100,000 yen or more each must in principle be recorded as fixed assets and depreciated over their useful life. Sole proprietors who file a blue return can, under the NTA's special provision for small-sum depreciable assets, expense assets costing less than 300,000 yen in a lump sum in the year of acquisition (up to a total of 3 million yen a year). When buying training equipment, consider making use of this provision.
Keeping Books and Supporting Documents
To record expenses, you need to keep supporting documents such as receipts and log them in your books. The retention period differs by filing method.
Category | Bookkeeping method | Document retention period |
|---|---|---|
White return | Single-entry bookkeeping (simplified records) | In principle 5 years (statutory books: 7 years) |
Blue return | Double-entry bookkeeping (for the 650,000 yen deduction) | In principle 7 years |
Choosing Between the Blue and White Return
Athletes who file as business income can choose either the blue return or the white return. If you have continuous income, the blue return — with its larger tax-saving benefits — is a strong candidate.
The Advantages of the Blue Return
The blue return comes with several benefits based on the NTA's blue-return system. The main advantages are as follows.
- Blue-return special deduction: if you keep double-entry books and file electronically (e-Tax), you can deduct up to 650,000 yen from your income
- Carrying losses forward: you can carry a loss forward for up to three years and offset it against profits in later years
- Salary to family: salary paid to family members who share your household can be expensed as salary for a blue-return full-time family employee
The more an athlete's income stabilizes, the greater the tax-saving effect of the blue return becomes. It is also effective with a view to your post-retirement career and asset building, and is worth considering alongside the perspective in Designing an Athlete's Second Career.
The Procedures a Blue Return Requires
Filing a blue return calls for an application in advance. The flow of the procedure is as follows.
- If you have started a business, submit the "Notification of Commencement or Discontinuance of a Sole Proprietorship"
- Submit the "Application for Approval of Blue Return" to the tax office by March 15 of the year you want to begin (or, for a new business, within two months of starting up)
- Separate your business account and card, and keep daily records using accounting software or the like
- File your tax return and blue-return financial statements during the following year's filing period (typically February 16 to March 15)
When a White Return Suits You
If your income is still small and you want to keep the administrative burden light, the white return is also an option. The white return gets by with simplified single-entry bookkeeping, but you cannot use the blue-return special deduction. A realistic approach is to switch to the blue return once your competitive activity gets into full swing and your income grows. For organizing how to turn competitive results into work, How to Build a Sports Athlete's Portfolio is also a helpful reference.
Summary
Filing taxes as an athlete starts from correctly understanding the income classification of each source. Here are the key points of this article.
- Professionals must in principle file; a company-employed athlete needs to file once non-salary income exceeds 200,000 yen a year
- Individually contracted sponsorship money (kyosankin) is, when it is continuous and independent, basically filed as business income
- Grant-type and loan-type scholarships are tax-free as a rule, but corporate grants and large gifts from individuals can be taxed
- Medal bonuses from the JOC, JPSA, and their member federations are tax-free up to a set amount; company bonuses and domestic prize money are taxable
- Record necessary expenses such as travel and equipment costs, and if you have continuous income, use the blue return to take advantage of the special deduction of up to 650,000 yen
Tax rules are revised every year, and the treatment changes with the details of each individual contract. When the judgment is difficult, always confirm it with your local tax office or a professional such as a tax accountant. This article is intended as general information and is not a substitute for individual tax advice.